' fill='%23cc0935'/%3E%3C/svg%3E)

' fill='%23cc0935'/%3E%3C/svg%3E)
'%3E%3Cg id='Group_1' data-name='Group 1' transform='translate(838.16 96.811)'%3E%3Cpath id='Path_1' data-name='Path 1' d='M13.382.347l-.563,7.2q-.709,8.68-1.336,19.87Q10.847,16.343,9.354.347H.8L5.482,39.063H17.81L21.94.347Zm9.927,38.716h8.115V.347H23.309V39.063Zm11.373,0h14.07V31.314H42.8V22.8h5.07V15.436H42.8V8.095h5.417V.347H34.682ZM73.752.347q-1.6,13.708-2.265,27.5l-.9-14.732Q69.872,2.045,69.706.346H61.28q-1.794,16.432-2.243,26.568l-.829-13.06L57.351.346H49.466L53.1,39.062H63.173q1.779-15.424,2.263-20.3,1.065,11.381,2.455,20.3H78.023L81.636.347H73.754Z' transform='translate(-0.796 -0.346)' fill='%231d1d1b' fill-rule='evenodd'/%3E%3C/g%3E%3Cpath id='Path_2' data-name='Path 2' d='M220.325,39.526h9.387q4.894,0,6.476-.693a4.349,4.349,0,0,0,2.3-2.584,17.387,17.387,0,0,0,.723-5.813V26.846a12.108,12.108,0,0,0-1-5.612,5.875,5.875,0,0,0-3.817-2.619,5.68,5.68,0,0,0,3.383-2.056,9.362,9.362,0,0,0,.858-4.732q0-5.018-1.214-7.276a6.076,6.076,0,0,0-3.19-3,17.414,17.414,0,0,0-5.811-.741h-8.1Zm9.8-31.874a1.5,1.5,0,0,1,.7.92,8.266,8.266,0,0,1,.27,2.546,14.619,14.619,0,0,1-.329,4.173q-.326.729-1.522.73c-.192,0-.462.009-.809.024V7.435a5.146,5.146,0,0,1,1.687.216Zm.55,15.016a6.148,6.148,0,0,1,.424,3.012v3.611a5.622,5.622,0,0,1-.473,2.94,2.983,2.983,0,0,1-2.188.67V22.07q1.811.073,2.236.6ZM252.456.813V29.34a17.806,17.806,0,0,1-.222,3.67.954.954,0,0,1-.993.777.882.882,0,0,1-.9-.705,14.1,14.1,0,0,1-.222-3.24V.813h-8.116V23.721q0,6.551.194,8.6a9.489,9.489,0,0,0,1.252,3.886,7.862,7.862,0,0,0,3.2,2.99,10.286,10.286,0,0,0,4.934,1.147,9.373,9.373,0,0,0,4.385-.969,7.527,7.527,0,0,0,3-2.846,9.45,9.45,0,0,0,1.369-3.658,55.93,55.93,0,0,0,.23-6.181V.813ZM280.907,11a20.617,20.617,0,0,0-.724-6.539,6.269,6.269,0,0,0-2.949-3.193A10.731,10.731,0,0,0,271.849,0a9.864,9.864,0,0,0-4.936,1.16,6.828,6.828,0,0,0-2.958,3.216,17.061,17.061,0,0,0-.916,6.5,16.667,16.667,0,0,0,.646,5.07,8.846,8.846,0,0,0,1.629,3.108,39,39,0,0,0,4.011,3.611,25.408,25.408,0,0,1,3.8,3.515q.752,1.053.752,4.472a5.417,5.417,0,0,1-.4,2.342,1.28,1.28,0,0,1-1.2.789,1.155,1.155,0,0,1-1.128-.621,7.543,7.543,0,0,1-.319-2.8v-4.71H263.29v2.535A24.491,24.491,0,0,0,264,34.911a7.084,7.084,0,0,0,3.017,3.9,9.815,9.815,0,0,0,5.562,1.531,10,10,0,0,0,5.2-1.328,6.8,6.8,0,0,0,3.015-3.288,17.6,17.6,0,0,0,.781-6.1q0-5.69-1.407-8.249t-6.826-6.548a6.74,6.74,0,0,1-2.293-2.368,7.716,7.716,0,0,1-.422-2.919,5.186,5.186,0,0,1,.376-2.25,1.193,1.193,0,0,1,1.108-.742,1.007,1.007,0,0,1,.965.55,6.874,6.874,0,0,1,.289,2.558v2.87h7.537V11Zm3.219,28.527h8.114V.813h-8.114ZM306.832.813V18.245L302.284.813H295.5V39.526h6.785v-17.6l4.221,17.6h7.113V.813Zm10.043,38.713h14.073V31.778H324.99V23.266h5.069V15.9H324.99V8.562h5.418V.812H316.875V39.526ZM350.473,11a20.642,20.642,0,0,0-.724-6.539A6.269,6.269,0,0,0,346.8,1.267,10.743,10.743,0,0,0,341.412,0a9.854,9.854,0,0,0-4.933,1.16,6.828,6.828,0,0,0-2.96,3.216,17.062,17.062,0,0,0-.916,6.5,16.7,16.7,0,0,0,.646,5.07,8.833,8.833,0,0,0,1.63,3.108,38.832,38.832,0,0,0,4.009,3.611,25.288,25.288,0,0,1,3.8,3.515q.753,1.053.752,4.472a5.417,5.417,0,0,1-.4,2.342,1.279,1.279,0,0,1-1.2.789,1.155,1.155,0,0,1-1.128-.621,7.55,7.55,0,0,1-.318-2.8v-4.71h-7.537v2.535a24.45,24.45,0,0,0,.713,6.719,7.078,7.078,0,0,0,3.016,3.9,9.816,9.816,0,0,0,5.562,1.531,10,10,0,0,0,5.2-1.328,6.8,6.8,0,0,0,3.016-3.288,17.62,17.62,0,0,0,.781-6.1q0-5.69-1.406-8.249t-6.826-6.548a6.729,6.729,0,0,1-2.294-2.368,7.716,7.716,0,0,1-.422-2.919,5.171,5.171,0,0,1,.376-2.25,1.192,1.192,0,0,1,1.108-.742,1,1,0,0,1,.964.55,6.853,6.853,0,0,1,.289,2.558v2.87h7.537V11Zm20.414,0a20.667,20.667,0,0,0-.724-6.539,6.274,6.274,0,0,0-2.95-3.193A10.742,10.742,0,0,0,361.825,0a9.856,9.856,0,0,0-4.935,1.16,6.826,6.826,0,0,0-2.959,3.216,17.048,17.048,0,0,0-.915,6.5,16.668,16.668,0,0,0,.646,5.07,8.8,8.8,0,0,0,1.629,3.108,38.884,38.884,0,0,0,4.008,3.611,25.312,25.312,0,0,1,3.8,3.515q.753,1.053.751,4.472A5.419,5.419,0,0,1,363.453,33a1.278,1.278,0,0,1-1.2.789,1.155,1.155,0,0,1-1.128-.621,7.57,7.57,0,0,1-.318-2.8v-4.71h-7.537v2.535a24.45,24.45,0,0,0,.713,6.719,7.075,7.075,0,0,0,3.016,3.9,9.816,9.816,0,0,0,5.561,1.531,9.993,9.993,0,0,0,5.2-1.328,6.8,6.8,0,0,0,3.017-3.288,17.62,17.62,0,0,0,.781-6.1q0-5.69-1.407-8.249t-6.825-6.548a6.737,6.737,0,0,1-2.294-2.368,7.733,7.733,0,0,1-.422-2.919,5.171,5.171,0,0,1,.376-2.25,1.191,1.191,0,0,1,1.108-.742,1,1,0,0,1,.963.55,6.842,6.842,0,0,1,.291,2.558v2.87h7.537V11Z' transform='translate(465.745 96)' fill='%23cc0935' fill-rule='evenodd'/%3E%3Cpath id='Path_3' data-name='Path 3' d='M0,.813V39.526H13.05V31.779H8.115V.812H0Zm18.3,0-4.14,38.714h8.39l.487-6.959h2.9l.435,6.959h8.293L30.026.813Zm4.634,24.892q.318-5.14,1.558-16.259.621,9.683,1.236,16.259ZM47.379.813V18.245L42.83.813H36.044V39.526H42.83v-17.6l4.221,17.6h7.113V.813H47.378Zm28.99,13.181a31.659,31.659,0,0,0-.732-7.987,7.966,7.966,0,0,0-3.066-4.287A9.711,9.711,0,0,0,66.653,0,9.588,9.588,0,0,0,61.98,1.112,8.178,8.178,0,0,0,58.8,4.161a9.993,9.993,0,0,0-1.378,4.03,62,62,0,0,0-.232,6.276v11.31a35.789,35.789,0,0,0,.752,8.525,7.574,7.574,0,0,0,3.065,4.435,10.093,10.093,0,0,0,5.879,1.6,8.894,8.894,0,0,0,5.773-1.891,8.513,8.513,0,0,0,3.026-4.407,36.619,36.619,0,0,0,.685-8.525V24.007H68.254v4.866a17.358,17.358,0,0,1-.28,4.051,1.267,1.267,0,0,1-2.4,0,15.435,15.435,0,0,1-.27-3.682V11.262a16.565,16.565,0,0,1,.27-3.825,1.191,1.191,0,0,1,1.272-.884,1.087,1.087,0,0,1,1.147.727,14.846,14.846,0,0,1,.261,3.662v6.728h8.115V13.993ZM81.577.812,77.438,39.526h8.389l.488-6.959h2.9l.436,6.959h8.291L93.308.813H81.577ZM86.213,25.7q.317-5.14,1.557-16.259.619,9.683,1.237,16.259H86.212ZM116.519,11a20.684,20.684,0,0,0-.723-6.54,6.262,6.262,0,0,0-2.95-3.192A10.725,10.725,0,0,0,107.459,0a9.84,9.84,0,0,0-4.935,1.16,6.826,6.826,0,0,0-2.958,3.215,17.064,17.064,0,0,0-.916,6.5,16.672,16.672,0,0,0,.646,5.07,8.862,8.862,0,0,0,1.629,3.108,38.959,38.959,0,0,0,4.009,3.61,25.357,25.357,0,0,1,3.8,3.515q.752,1.053.752,4.472a5.4,5.4,0,0,1-.4,2.343,1.278,1.278,0,0,1-1.2.789,1.155,1.155,0,0,1-1.128-.621,7.556,7.556,0,0,1-.318-2.8V25.657H98.9v2.534a24.506,24.506,0,0,0,.712,6.72,7.083,7.083,0,0,0,3.017,3.9,9.828,9.828,0,0,0,5.561,1.53,10.011,10.011,0,0,0,5.2-1.326,6.8,6.8,0,0,0,3.017-3.289,17.639,17.639,0,0,0,.781-6.1q0-5.692-1.407-8.25t-6.825-6.548a6.735,6.735,0,0,1-2.294-2.367,7.722,7.722,0,0,1-.422-2.919,5.186,5.186,0,0,1,.376-2.25,1.192,1.192,0,0,1,1.108-.742,1,1,0,0,1,.964.549,6.856,6.856,0,0,1,.289,2.559v2.868h7.537V11ZM130.283.813V14.658h-2.429V.813h-8.115V39.526h8.115V23.266h2.429V39.526H138.4V.813Zm11.373,38.714h8.115V.813h-8.115Zm11.372,0h8.115V22.071q1.676,0,2.072.741a10.845,10.845,0,0,1,.4,3.85V39.526h7.536V29.316a44.475,44.475,0,0,0-.2-5.727,6.461,6.461,0,0,0-1.03-2.283,5.808,5.808,0,0,0-3.239-1.985q2.66-.312,3.566-1.865t.905-6.074q0-4.949-1.281-7.209a5.481,5.481,0,0,0-3.316-2.81,35.563,35.563,0,0,0-7.777-.55h-5.744V39.526ZM163.079,8.01a3.786,3.786,0,0,1,.531,2.415v2.128q0,2.56-.55,3.025a3.011,3.011,0,0,1-1.918.466V7.437A2.589,2.589,0,0,1,163.079,8.01Zm11.208,31.516h14.071V31.779H182.4V23.266h5.069V15.9H182.4V8.56h5.416V.813H174.288V39.526Z' transform='translate(495 96)' fill='%231d1d1b' fill-rule='evenodd'/%3E%3C/g%3E%3C/svg%3E)
'%3E%3Ccircle id='Frame' cx='12.5' cy='12.5' r='12.5' transform='translate(24.695 28)' fill='%23cc0935'/%3E%3Cpath id='Icon_awesome-linkedin-in' data-name='Icon awesome-linkedin-in' d='M3.358,15H.248V4.986h3.11ZM1.8,3.62A1.81,1.81,0,1,1,3.6,1.8,1.816,1.816,0,0,1,1.8,3.62ZM15,15h-3.1V10.125c0-1.162-.023-2.652-1.617-2.652-1.617,0-1.865,1.262-1.865,2.568V15H5.306V4.986H8.288V6.352h.044a3.268,3.268,0,0,1,2.942-1.617C14.421,4.735,15,6.807,15,9.5V15Z' transform='translate(29.695 33)' fill='%23fff'/%3E%3C/g%3E%3C/svg%3E)
'%3E%3Ccircle id='Frame' cx='12.5' cy='12.5' r='12.5' transform='translate(109.695 28)' fill='%23cc0935'/%3E%3Cpath id='Icon_awesome-facebook-f' data-name='Icon awesome-facebook-f' d='M10.618,10.125l.5-3.258H7.992V4.753a1.629,1.629,0,0,1,1.837-1.76H11.25V.22A17.329,17.329,0,0,0,8.728,0C6.153,0,4.471,1.56,4.471,4.385V6.867H1.609v3.258H4.471V18H7.992V10.125Z' transform='translate(116.086 32)' fill='%23fff'/%3E%3C/g%3E%3C/svg%3E)
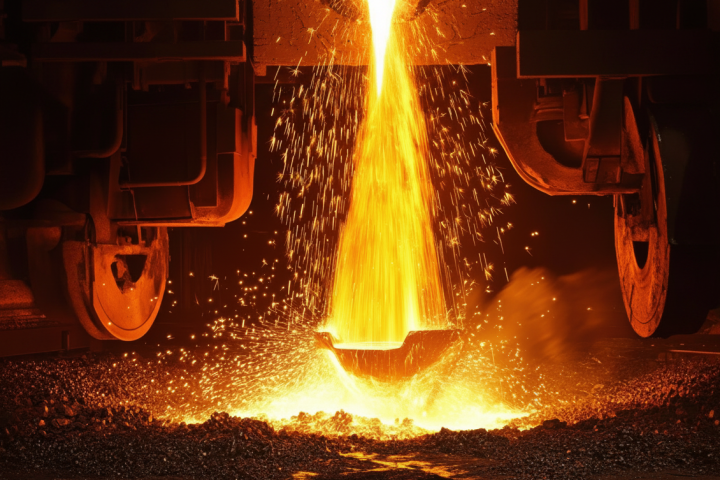
When an industrial site closes, Westminster often writes it off as an unfortunate casualty of global market forces. But speak to the communities, the supply chains, and the engineering firms left behind, and the narrative looks very different.
The steady erosion of British industrial capacity isn’t an accident of history. It is a slow motion unraveling caused by decades of uncompetitive energy policy, prohibitive power tariffs, and a refusal to treat foundational manufacturing as a strategic asset. For regions like Lancashire and the industrial North, the trail of closures isn’t just a series of headlines; it’s a warning of what happens when base industry is priced out of existence.
The current crisis did not emerge overnight. The warning lights have been flashing red across the UK’s industrial map for over fifteen years:
- Primary Metals Lost (2009–2012): The closure of the Anglesey Aluminium and Lynemouth smelters brought an unceremonious end to major primary aluminium smelting in the UK, handing domestic demand straight to overseas competitors.
- The Redcar Catastrophe (2015): The collapse of SSI Steel at Redcar wiped out 1,700 direct jobs and gutted an entire regional supply chain overnight, demonstrating the sheer vulnerability of heavy industry without a competitive operational framework.
- Chemical Fragility (2023): CF Fertilisers halted ammonia production at Billingham, crippled by soaring natural gas prices. The ripple effect touched everything from domestic CO₂ supply to agriculture and the food-processing sector.
- The Blast Furnace Crisis (2024–2025): Port Talbot’s blast furnaces cooled for the last time, Grangemouth halted crude refining, and emergency parliamentary interventions were required simply to keep Scunthorpe from the edge. A G7 nation found itself teetering on the brink of losing the ability to make primary virgin steel from scratch.
The most dangerous misconception in modern policy is that this is simply the decline of ‘dirty’ legacy industry making way for a high-tech, green economy. The reality is that advanced green technology requires immense, affordable energy infrastructure to function:
- The Britishvolt Collapse: Northumberland’s promised gigafactory imploded, stranding the UK’s ambitions to anchor domestic battery supply chains for electric vehicles.
- The Liverpool Life Sciences Blow: AstraZeneca abruptly halted a planned £450 million state-of-the-art vaccine facility in Speke, citing punitive domestic energy costs and shifting state backing, choosing to take investment overseas instead.
When high-value pharmaceutical giants and clean-tech battery pioneers decide the UK grid is too expensive to power modern operations, the argument shifts. This is no longer about managing the decline of Victorian-era assets; it is about poisoning the well for future growth.
Manufacturing and engineering in Lancashire have continually adapted, but resilience is not an infinite resource. If we hollow out the foundational supply chains—the metals, the chemicals, the basic processing—we make the entire regional economy fragile. You cannot build a modern aerospace component, an advanced automotive part, or a renewable turbine without domestic raw materials and a functioning local supply network.
Stopping this casualty list from expanding requires more than warm words from Whitehall. It demands an energy regime that treats power as an economic catalyst rather than a balance-sheet penalty.
For regional businesses, waiting for systemic reform is no longer a viable strategy. Operational survival now hinges on taking control of energy overheads directly: auditing tariffs, generating power behind the meter, securing private-wire arrangements, and insulating sites from an uncompetitive national grid.
Discover practical strategies to cut commercial exposure and protect your bottom line at RMB&Co.
' fill='%23cc0935'/%3E%3C/svg%3E)
' fill='%23cc0935'/%3E%3C/svg%3E)
Enjoyed this? Read more from RMB & Co. Limited